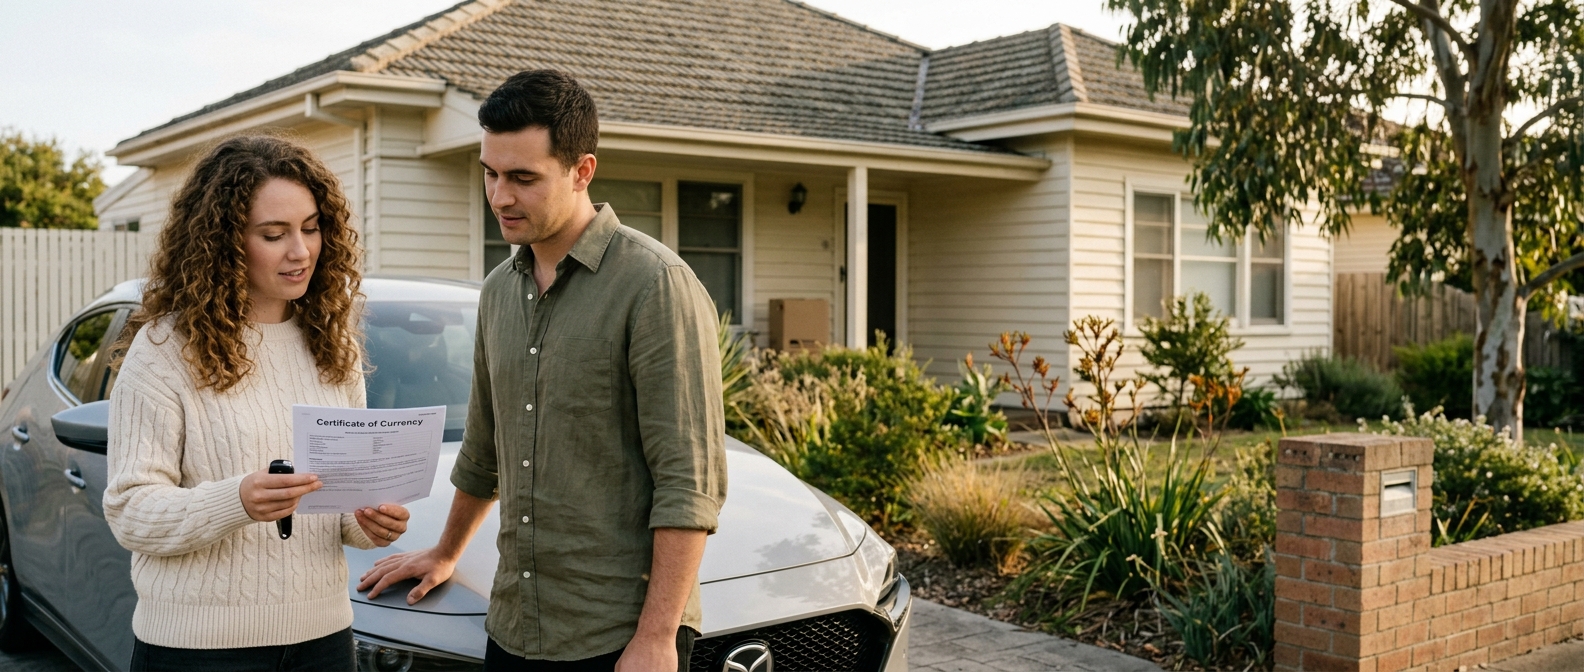
Your postcode is a pricing input, and moving can change your premium. Tell your insurer your new address, then re-quote on the new postcode and pay what your suburb actually says you should.
What changes when you move
Your premium follows the postcode, not the policy number.
Your address re-prices
Insurers price by postcode.
Where you live and where the car is kept are pricing inputs, so a new suburb may shift the premium: sometimes up, sometimes down. Insurers use the address where the car sleeps, not just your mailing address.
CTP changes by state
Interstate move = new CTP (Green Slip in NSW).
Compulsory Third Party (CTP) cover is regulated state-by-state. Moving NSW → QLD or VIC → SA means a new CTP arrangement, and a few states bundle it into rego, others don’t.
Lender may require comprehensive
Financed car? Cover’s likely mandatory.
If your car has a loan against it, the lender is likely to require comprehensive cover with their interest noted. Verify your new postcode policy still meets the lender’s requirements.
NestPath
×
Car insurance premiums can vary significantly across insurers for the same vehicle, driver and postcode, so it is worth re-quoting after a move and comparing the cover side by side.
Compare the Market shows you live Australian premiums by postcode, vehicle and driver profile across a range of brands, side-by-side.
Empowering Aussies, one comparison at a time
We believe the best decisions start with a comparison. That's why our team has spent over a decade helping millions of Aussies compare prices and search for a better deal.
We strive to empower our customers to make better choices, saving them time, money and stress.
4.4/5 on Product Review (3,348 reviews) · 4.7/5 on Feefo (2,836 reviews) · 23 million comparisons, across all Compare the Market comparison services. Ratings as of 15/07/2026.
Why we partner with CTM for car insurance
The same car at the same new postcode can cost noticeably more with one insurer than another for comprehensive cover. Compare the Market helps you compare a range of brands and policies, and you can set your excess to suit when you take out the new policy.
NestPath earns a commission if you take out a policy through Compare the Market. No extra cost to you, and it doesn't change the comparison results you see. Affiliate revenue keeps NestPath free for first home buyers.
Compare The Market does not compare all plans in the market. See their website to view their range of brands.
Free to useNo obligationCompare the Market Australia
How to compare car insurance quotes like for like
To compare car insurance like for like, get every quote for the same car, the same drivers, the same address and the same type of cover, then check the same points in each product disclosure statement (PDS): how the car is valued, the excess, the exclusions and the extras. Moneysmart says the things covered and cost of the policy can vary a lot between different insurers.
Built from Moneysmart's “Choosing car insurance” and “How to save money on car insurance” pages (ASIC), last updated 23 October 2026. Check the PDS for each policy.
Keep the same in every quote
Why it matters
Type of cover
Comprehensive, third party property damage, and third party property damage, fire and theft cover different things, so a lower quote can simply be less cover.
The car and how you use it
Moneysmart says the premium takes into account the type and value of the car, who will be driving it, and how often and far you drive it.
Listed drivers
Add the same drivers to every quote. Check whether an extra excess applies to younger or less experienced drivers.
Address and where the car is kept
Moneysmart lists where you live and where you keep the car as pricing inputs.
Agreed value or market value
This sets what you get if the car is written off or stolen. Use the same choice, and the same amount for agreed value.
Excess
Moneysmart says to weigh up a higher premium and lower excess against the opposite. Quote the same excess everywhere first.
Extras
Roadside assistance, towing, car hire, accommodation and cover for items stolen from the car can be included or extra. Compare like with like.
Then compare the exclusions, to see what isn't covered. Moneysmart gives these examples: mechanical failure, depreciation, rust, or wear and tear; intentional damage (for example, vandalism); damage caused by an unlicensed, drunk, or drug-affected driver; and storm damage. It also says to check if the insurer always charges an excess, even if an accident isn't your fault.
Moneysmart also points out that the insurance brand you buy from and the underwriter behind it can differ, and the same underwriter might sell policies with the same cover at different prices under different brand names. Compare the cover, not just the name.
NestPath earns a commission if you take out a policy through Compare the Market. No extra cost to you, and it doesn't change the comparison results you see. Affiliate revenue keeps NestPath free for first home buyers. *Compare The Market does not compare all plans in the market. See their website to view their range of brands.
Why moving house re-prices your car insurance
Australian insurers price car insurance using your address, the postcode where the car sleeps most nights, as one of the pricing inputs. Moneysmart lists the others: the type and value of the car, who will be driving it, how often and far you drive it, and where you keep the car. Moneysmart suggests asking your insurer whether changes such as moving to a safer suburb or secure parking should lower your premium, so a new address may change the premium when you move.
Important: tell your insurer. Check what your PDS says you must tell the insurer during the policy, and answer its questions accurately when you buy or renew. Under the Insurance Contracts Act you have a duty to take reasonable care not to make a misrepresentation before the contract is entered into. If you don't, and the insurer would not have offered the same cover on the same terms had it known, it can reduce what it pays on a claim, or avoid the contract if the failure was fraudulent. Tell your insurer the new address as its policy requires, with the change dated to the day the car moves to the new address.
Comprehensive vs Third Party vs CTP: what each one does
Three different products, frequently confused:
CTP
Mandatory by law in all Australian states and territories
Covers injuries to people caused by your car
Does NOT cover damage to vehicles or property
You choose your CTP insurer in NSW (Green Slip), QLD, SA and ACT; in VIC, TAS, WA and NT it is included with rego
Third Party Property
Optional cover that may cost less than comprehensive, and covers less
Covers damage YOU cause to other people’s vehicles + property
Does NOT cover damage to your own car
Third party property damage, fire and theft adds cover if your car is stolen or damaged by fire
Comprehensive
Covers damage to your car AND others
Includes theft, fire and weather damage, plus damage you cause to other people's cars or property
Usually needed if you want cover for repairs to your car after a crash you cause (Moneysmart)
Likely required by your lender if the car is financed: check the loan contract
Comprehensive vs third party property vs third party, fire and theft
Comprehensive car insurance covers damage to your car and to other people's cars or property, even if you caused the accident, plus theft, fire and weather damage. Third party property damage covers only damage your car causes to other people's cars or property. Third party property damage, fire and theft adds cover if your car is stolen or damaged by fire.
Source: Moneysmart (ASIC), “Choosing car insurance”, last updated 23 October 2026. Every policy has exclusions: check the PDS.
What happens
Comprehensive
Third party property, fire and theft
Third party property
CTP (Green Slip in NSW)
Your car damages someone else's car or property
Covered
Covered
Covered
Not covered
Your car is stolen or damaged by fire
Covered
Covered
Not covered (some policies let you pay extra)
Not covered
Damage to your car in an accident you caused
Covered
Not covered
Not covered
Not covered
Your car is damaged by weather
Covered
Not covered
Not covered
Not covered
Injuries to people caused by your car
Covered by CTP, not by these policies
Covered
How the car is valued if written off or stolen
Agreed value or market value (you choose)
Check the PDS for how a stolen or burnt out car is valued
Not applicable: no cover for your own car unless you pay extra for fire and theft
Not applicable: no vehicle damage cover
Moneysmart's test for choosing: think about whether you can get by without your car if it's written off or stolen, and whether you can afford to pay for the damage to someone else's car if you have an accident. It also says that if you want insurance that covers the cost of repairs to your car after a crash you cause, you usually need comprehensive car insurance.
With comprehensive car insurance you can choose how your car is valued, and the value is the amount you get if the car is written off or stolen. Moneysmart defines the two options:
Agreed value: a fixed amount decided by you and your insurer. As the car gets older, the insurer may reduce the agreed value every year, so check it at each renewal.
Market value: the amount your car would have sold for at the time of the accident, decided by the insurer based on industry information. It is not the amount you think you could sell it or trade it in for.
The trade off, in Moneysmart's words: if you use the market value, you don't know how much you'll get if you claim, and you can't change the amount. If you use an agreed value, you'll pay a higher premium. Moneysmart's example is a driver whose agreed value fell each year at renewal while the premium went up, so the write off payout was well below what she paid for the car. When you compare quotes, use the same valuation method and amount in each one.
Car insurance by state: NSW, VIC, QLD and the rest
In every state you buy comprehensive and third party property cover from an insurer, and Moneysmart lists where you live and where you keep the car among the pricing inputs. What changes by state is the compulsory injury cover (CTP) you need to register the car, and the rules for registering your car after you move. CTP is not compared by Compare the Market: each state and territory runs its own scheme, linked below.
Car insurance in NSW
In NSW, SIRA says that before you can register any vehicle you must buy a Compulsory Third Party (CTP) insurance policy, commonly known as a Green Slip. You buy it directly from a licensed insurer, or through agents, outlets and online, and you can generally choose a 12-month or a 6-month policy. The Green Slip Price Check from Service NSW gives a CTP Green Slip quote comparison from all insurers for the most common vehicle types. Service NSW notes that a driving offence in the past 3 years and 4 months that added demerit points could affect the cost of your Green Slip.
A Green Slip does not cover the cost of repairing or replacing your vehicle or other property, so damage to cars is covered only by a separate comprehensive or third party property policy, which is what you compare through Compare the Market. If you've moved to NSW from another state or territory, Service NSW says you need to register your vehicle in NSW, and you can only drive in NSW on an interstate licence for 3 months.
NestPath earns a commission if you take out a policy through Compare the Market. No extra cost to you, and it doesn't change the comparison results you see. Affiliate revenue keeps NestPath free for first home buyers. *Compare The Market does not compare all plans in the market. See their website to view their range of brands.
Registering your car after an interstate move
Sources: Service NSW, VicRoads, Queensland Government, Transport WA, SA.GOV.AU, Transport Tasmania, Access Canberra and NT.GOV.AU registration pages, read 1 November 2026. Rules change: check the official page before you move.
Moving to
What the state says about registering your car
Official page
NSW
You need to register your vehicle in NSW. An interstate licence can be used in NSW for 3 months.
VicRoads sets out how to register a vehicle from another state; no deadline is given on that page. Convert an interstate licence within six months of residing in Victoria.
If the car's permanent address is in the ACT, you need to register it in the ACT, including when you move to the ACT with an interstate registered car. The 3 month exemption is only for a car temporarily kept in the ACT and registered elsewhere.
Whatever the state, tell your car insurer the new address and where the car will be kept, then compare quotes on the new postcode.
CTP by state: what to update when you move
CTP is regulated state-by-state in Australia. Each state runs its own scheme with different providers, pricing rules and registration bundling. If you cross a border, your CTP arrangement changes. CTP is not compared by Compare the Market, so use the state scheme linked in the table.
Sources: each state and territory's CTP regulator or registration authority, read 1 November 2026. Check the destination state's transport authority for the exact rules.
State / territory
Local name
Bundled with rego?
How to update after a move
Scheme
NSW
Green Slip
No, buy it before you register
Re-register vehicle to NSW + buy new Green Slip from a licensed insurer
Cross-state move action list: book the rego transfer at your destination state's transport authority (Service NSW, VicRoads, TMR, etc.) within that state's deadline (see the table above), then re-quote your comprehensive cover: a move may change your quote, so compare on the new postcode.
NestPath earns a commission if you take out a policy through Compare the Market. No extra cost to you, and it doesn't change the comparison results you see. Affiliate revenue keeps NestPath free for first home buyers. *Compare The Market does not compare all plans in the market. See their website to view their range of brands.
Your claims history when you switch insurers
A clean claims history is one of the most valuable things you carry between policies. Insurers ask about your claims and insurance history when you get a quote, and where a policy has a no claim bonus or rating, Moneysmart says insurers may consider your claims history, including any claims by other drivers on your policy, and your rating from your previous car insurer. How a past claim affects the price differs between insurers, and Moneysmart notes that even if you're not at fault, insurers may increase your premium after you make a claim.
When you switch: answer the new insurer's claims-history questions accurately at quote time, as they may verify your record. If an insurer asks for proof, a Letter of Experience or Claims History Letter from your old insurer does the job. Check the quote reflects the history you gave before you pay.
If you need to claim: what the insurer must do
After you've made your claim, Moneysmart says the insurer must contact you within 10 business days. They may accept or reject your claim or ask for more information, and if they reject your claim, they must do this in writing. If you're not happy with how your insurer has handled your claim, make a complaint to their internal dispute resolution team, and if you're still not happy, contact the Australian Financial Complaints Authority (AFCA).
Check your policy first: what you can claim for depends on the type of car insurance you have. With third party property damage, for example, you can claim only for damage to other people's cars or property, subject to the policy. Your insurer may need the location of the accident, a description of what happened and any damage (plus photos), a police report number if police attended, tow truck details and witness contact details.
How excess works, and how a higher excess can cut the premium
The excess is the amount that you pay when you make a claim (Moneysmart's definition). Your policy sets out the excess amount (your policy may call this the basic excess) and may let you choose a higher excess to lower the premium. Some policies add other excesses in certain situations, for example:
Age or young driver excess when a younger driver is driving at the time of the claim
Inexperienced driver excess for drivers who have held a full licence for less than a set number of years
Imposed excess for high-risk vehicles or drivers (history of claims)
Moneysmart says a higher excess may reduce your premium, but you will need to be able to pay the excess if you make a claim. It also says that generally you have to pay an excess when you make a claim whether you're at fault or not, and some policies will waive the excess in limited circumstances, so check the PDS for the excess amount and the conditions where it might be waived.
The excess also shapes when a claim is worth making. Moneysmart's example: a driver with a $650 excess was told by her insurer that a scratch would probably cost $400 to repair, so paying for the repair herself cost less than claiming. Ages, licence years and excess amounts differ by policy, so quote every policy with the same drivers and the same excess.
If your car is on finance: what your lender requires
A secured car loan is likely to require the vehicle to carry comprehensive insurance with the lender’s interest noted, and Moneysmart suggests asking whether there is a minimum level of insurance the lender requires. Check the loan contract. The lender may ask for proof at:
Loan settlement: certificate of currency before they release funds
Each annual renewal: updated certificate showing continuous cover
Any policy change: if you switch insurers and the loan contract requires it, the new certificate should show the lender’s interest
When you switch insurers after a move, tell the new insurer about the finance arrangement at quote time so the lender’s interest is noted from day one, and forward the new certificate to the lender promptly so their records show continuous cover.
Add-on insurance with a car or a loan. Moneysmart says salespeople can tell you about add-on insurance during your car purchase, but they must wait four days before selling it to you, and you do not have to buy it. If they don't wait, you have the right to cancel the insurance and get a full refund. One example is guaranteed asset protection (GAP) insurance: if you write off your car, it pays the lender if there's a gap between what you owe and what you get from comprehensive car insurance. Moneysmart also notes that most add-on insurance premiums are included in your car loan, and interest charges make premiums even more expensive.
How to apply: a 5-step process
Update your address on the current policy. Date the change to the day the car moves to the new address so cover is continuous.
Know your claims history: if your new insurer asks for proof, a Letter of Experience from your current insurer does the job.
Compare via Compare the Market. Free for you, takes minutes. Have your new postcode, vehicle details, claims history and excess preference in mind.
Pick a policy. If the car is financed, confirm the new policy notes the lender’s interest.
Set a 12-month reminder to re-shop.
NestPath earns a commission if you take out a policy through Compare the Market. No extra cost to you, and it doesn't change the comparison results you see. Affiliate revenue keeps NestPath free for first home buyers. *Compare The Market does not compare all plans in the market. See their website to view their range of brands.
Other things to compare
While you’re here
Our Compare the Market partnership also covers these verticals. Explore them all in the Insurance Hub.
These links open our Insurance Hub guides. NestPath earns a commission if you take out a policy or plan through Compare the Market from those guides, at no extra cost to you. Same disclosure as the main partnership block above.
*Compare The Market does not compare all plans in the market. See their website to view their range of brands.
Got a question we haven’t answered?
Drop the details and we’ll reply within 24 hours with a straight answer, not a sales pitch. If Compare the Market is the right next step for your situation, we’ll tell you. If it’s not, we’ll tell you that too.
NestPath earns a commission if you take out a policy through Compare the Market. No extra cost to you, and it doesn't change the comparison results you see. Affiliate revenue keeps NestPath free for first home buyers. *Compare The Market does not compare all plans in the market. See their website to view their range of brands.
Car insurance for Australian homeowners: common questions
How do I compare car insurance quotes like for like?
Get every quote for the same car, the same listed drivers, the same address and place the car is kept, and the same type of cover, with the same valuation (agreed or market value) and the same excess. Then check the same points in each PDS: exclusions, extras such as roadside assistance or a hire car, and when an excess applies. Moneysmart says the things covered and cost of the policy can vary a lot between different insurers.
What is third party property, fire and theft car insurance?
Moneysmart says third party property damage, fire and theft includes the same cover as third party property damage, plus it covers your car if it's stolen or damaged by fire. It does not cover damage to your own car in an accident you cause or weather damage to your car; for that you usually need comprehensive car insurance.
Do I need to update my car insurance when I move house in Australia?
Yes. Moneysmart says the insurer works out your premium taking into account where you live and where you keep your car, so a move can change the price. Check what your PDS says you must tell the insurer during the policy, and answer its questions accurately when you buy or renew: under the Insurance Contracts Act, if you don't take reasonable care to avoid a misrepresentation and the insurer would not have offered the same cover on the same terms had it known, it can reduce what it pays on a claim. Date the address change to the day the car moves to the new address so cover is continuous on the new postcode.
What is the difference between CTP, third party property and comprehensive car insurance?
CTP (Compulsory Third Party / Green Slip in NSW) is mandatory by law and covers injuries to people caused by your car: it does NOT cover any vehicle damage. Third party property is optional cover for damage you cause to other people's vehicles and property: it does NOT cover your own car. Comprehensive covers damage to your car AND damage you cause to others, even if you caused the accident, plus theft, fire and weather damage. Moneysmart says that if you want insurance that covers the cost of repairs to your car after a crash you cause, you usually need comprehensive car insurance.
Do I need new CTP if I move interstate?
Yes. CTP is regulated state-by-state in Australia. Each state runs its own scheme with different insurers and pricing rules. Moving NSW to QLD, VIC to SA, or any interstate move requires re-registering your vehicle at the destination state's transport authority (Service NSW, VicRoads, TMR Queensland, etc.). You choose your CTP insurer in NSW (Green Slip), QLD, SA and ACT; in VIC, TAS, WA and NT it is included with registration (the TAC charge, MAIB, Motor Injury Insurance and MAC insurance). The destination state's transport authority handles the transition.
How long do I have to register my car after moving interstate?
It depends on the state you move to. Queensland gives you 14 days to register your vehicle and says you may be fined if you don't. SA says to register within 3 months, Tasmania lets an interstate registered vehicle be used for three months, and the NT says within 3 months of living there, or within 28 days of arriving if you have or have applied for an NT driver licence. NSW says you need to register your vehicle in NSW, and Victoria and WA explain how to register (license) an interstate vehicle without a fixed deadline on those pages. Check the transport authority's page for the current rules before you move.
Will my no-claim bonus transfer if I switch insurers?
It depends on the insurer. Moneysmart says that to calculate a no claim bonus, insurers may consider how long you (and any other drivers on your policy) have been driving, your claims history, including any claims by other drivers on your policy, and your rating from your previous car insurer, and how a claim affects your price differs between insurers. Answer the claims-history questions accurately when you compare, and if an insurer asks for proof, request a Letter of Experience or Claims History Letter from your current insurer.
Why is comprehensive car insurance required by my lender?
When you finance a car with a secured loan, the lender takes the vehicle as security against the debt. If the car is damaged or destroyed, the lender needs the insurance payout to cover the outstanding loan balance: that's why a lender is likely to require comprehensive cover (not just third party) with their financial interest noted on the policy. Moneysmart suggests asking whether there is a minimum level of insurance the lender requires, so check the loan contract for what cover it needs and for how long.
How much does car insurance cost per year in Australia?
Wide range, because the price is built from your details. Moneysmart says the insurer works out your premium taking into account the type and value of the car, who will be driving it, how often and far you drive it, where you live and where you keep the car, plus the type of insurance and the excess you choose. Higher-risk vehicles, higher-risk postcodes and additional drivers can all lift the premium. Our guide to how much car insurance costs in Australia (linked on this page) covers the price factors in more detail; for your own price, compare quotes on the same cover.
What is a young driver excess and when does it apply?
Some policies add an age or young driver excess for a claim when a younger driver was driving, and some add an inexperienced driver excess for drivers who have held a full licence for less than a set number of years. Whether these apply, and whether they add to the standard excess, depends on the policy, as do the ages, licence years and amounts, so check the PDS. If you have a teen driver in the household, this can lift the effective per-claim cost: list every driver and factor it into the comparison.
What is agreed value vs market value cover?
Both decide what you get if the car is written off or stolen. Moneysmart defines agreed value as a fixed amount that's decided by you and your insurer, and says that as your car gets older, your insurer may reduce the agreed value every year, so check it at each renewal. Market value is the amount your car would have sold for at the time of the accident, decided by your insurer based on industry information. With market value you don't know how much you'll get if you claim; with an agreed value you'll pay a higher premium.
How do I cancel my old car insurance policy after switching?
Call the old insurer or use their online cancellation form; the PDS explains how to cancel, the cooling-off period, and how refunds and any cancellation fee work after it. Insurers that subscribe to the General Insurance Code of Practice say that if you are entitled to a refund and you cancel, they will return the amount within 15 business days; if you arranged the insurance through an insurance broker, different arrangements apply. Check the exact start time of the new policy and the end time of the old one so there is no gap in cover. If your car is financed, tell the lender about the switch and forward the new certificate of currency with their interest noted.
How often should I re-shop my car insurance?
Annually. Moneysmart says it's important to consider annually if it's still the best deal for you, and to check your renewal notice carefully. A reminder a few weeks before renewal gives you time to compare quotes on the same cover. Comparing via Compare the Market takes only a few minutes with details you already have on hand.
NestPath earns a commission if you take out a policy through Compare the Market. No extra cost to you, and it doesn't change the comparison results you see. Affiliate revenue keeps NestPath free for first home buyers. *Compare The Market does not compare all plans in the market. See their website to view their range of brands.
When will my car insurer send a renewal notice?
The Insurance Contracts Act says that not later than 14 days before renewable cover under a general insurance contract expires, the insurer must give you a notice in writing. Insurers that subscribe to the General Insurance Code of Practice say that if they offer to renew a motor vehicle policy you bought directly from them (not a fleet or business policy), the renewal notice compares this year's and last year's premium and explains how it is calculated. Moneysmart says to check your renewal notice carefully and compare insurers.
Is CTP (Green Slip in NSW) part of the Compare the Market comparison?
No. CTP is not compared by Compare the Market. CTP is run state by state: in NSW, the Green Slip Price Check from Service NSW gives a CTP Green Slip quote comparison from all insurers for the most common vehicle types, and the other states and territories run their own schemes through registration (the CTP by state table on this page links each scheme). Compare the Market compares comprehensive and third party car insurance.
NestPath earns a commission if you take out a policy through Compare the Market. No extra cost to you, and it doesn't change the comparison results you see. Affiliate revenue keeps NestPath free for first home buyers. *Compare The Market does not compare all plans in the market. See their website to view their range of brands.
Do I have to pay the excess if the accident was not my fault?
Generally, yes. Moneysmart says that generally, you have to pay an excess when you make a claim whether you're at fault or not, and some policies will waive the excess in limited circumstances. Its example is a driver hit by someone who drove off, whose policy said she had to pay the excess if the at fault party couldn't be found. Check the PDS for the excess amount and the conditions where it might be waived.
How long does a car insurer have to respond to a claim?
Moneysmart says that after you've made your claim, the insurer must contact you within 10 business days. They may accept or reject your claim or ask for more information, and if they reject your claim, they must do this in writing. If you're not happy with how your claim was handled, complain to the insurer's internal dispute resolution team first, then to the Australian Financial Complaints Authority (AFCA).
Also worth a look: car insurance is one of three policies your new postcode quietly re-prices. Our home insurance guide covers the building + contents side, and our utilities guide covers the electricity / gas re-connect on move-in day. Some insurers or energy retailers may offer a multi-policy discount when you bundle two or more.
Reviewed by Anish Puri, NestPath founder · Last reviewed 1 November 2026 · Editorial, never paid placement · ABN 88 688 597 480