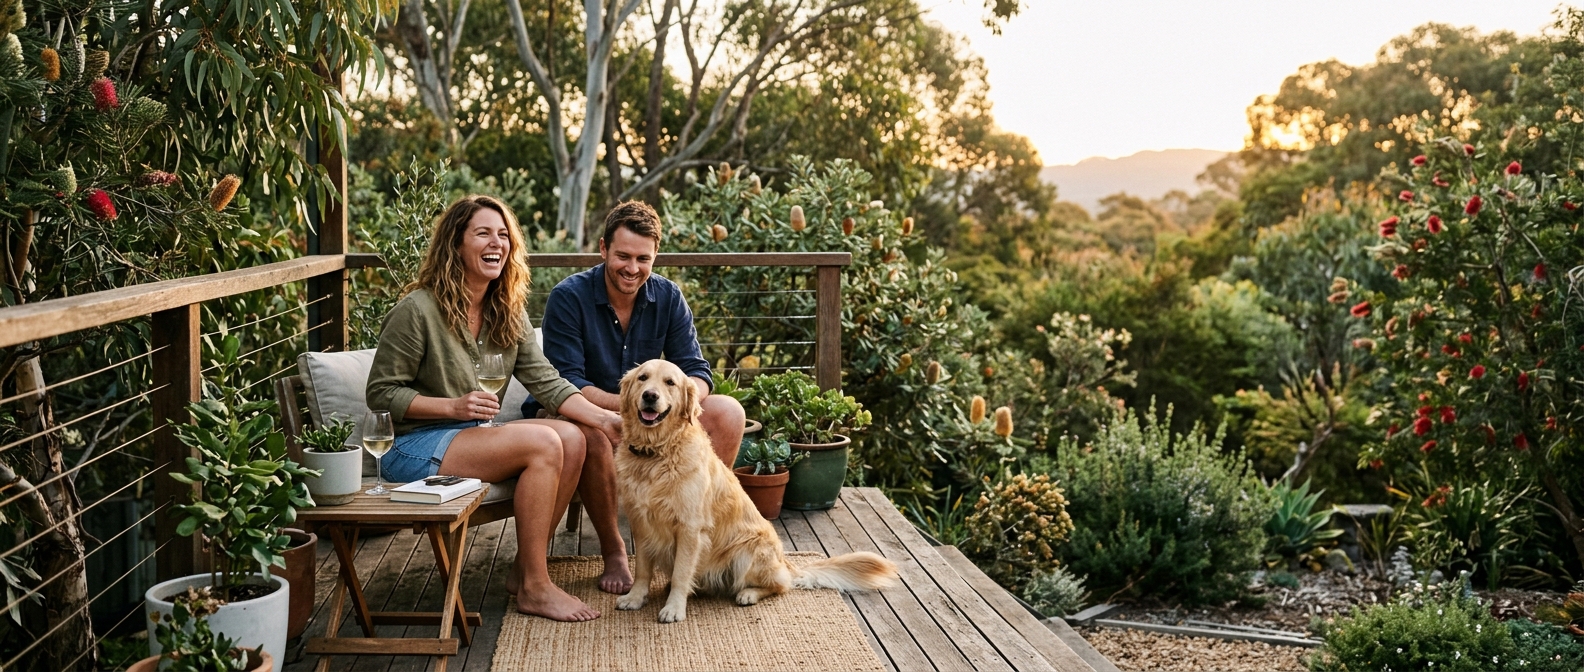
Australian couple seated on the back deck of their cream weatherboard home with a golden retriever beside them, native garden behind, warm afternoon golden light
The bill nobody budgets for

Compare pet insurance in Australia

Pet insurance, for the $7,000 surprise.

An emergency vet bill in Australia routinely costs $3,000 to $7,000. The monthly premium isn’t the problem: the rare $7,000 cruciate-ligament repair, snake-bite emergency, or specialist surgery is. Pet insurance is the budget defence to help with the bill you can’t predict.

What pet insurance actually is for

The monthly premium isn’t the problem. The $7,000 emergency is.

Typical emergency bill

$3,000 to $7,000.

Cruciate ligament repair, snake bite anti-venom, tick paralysis treatment, ingestion emergencies, hit-by-car trauma. Any of these routinely cost $3,000 to $7,000 in metro Australian specialist clinics.

Waiting periods bite

Get cover BEFORE.

Common waiting periods include 30 days for illness, 6 months for cruciate ligament conditions and 12 months for some orthopaedic conditions (indicative; check the PDS). The cover you take out today only kicks in after these periods. Lock it in early.

Pre-existing exclusions

Once it’s on file, it usually stays out.

Any condition diagnosed before a policy is taken out is generally excluded. The younger and healthier your pet at policy commencement, the fewer exclusions you’re likely to carry.

NestPath
Compare the Market

Pet insurance premiums can vary significantly across Australian insurers for the same breed, age and cover level, so it’s worth comparing before you commit.

Compare the Market shows accurate premiums by breed, age and cover level across a range of pet insurance brands, side-by-side.

Empowering Aussies, one comparison at a time

We believe the best decisions start with a comparison. That's why our team has spent over a decade helping millions of Aussies compare prices and search for a better deal.

We strive to empower our customers to make better choices, saving them time, money and stress.

4.4/5 on Product Review (3,348 reviews) · 4.7/5 on Feefo (2,836 reviews) · 23 million comparisons, across all Compare the Market comparison services. Ratings as of 15/07/2026.

Why we partner with Compare the Market for pet

There can be a wide range in premiums for pet insurance policies offering very similar cover, and comparing lets you review those differences. Always check the PDS and know the inclusions and exclusions: a cheap policy could cost you dearly if the cover is less than your vet bills.

Compare pet insurance

NestPath earns a commission if you take out a pet insurance policy through Compare the Market. No extra cost to you, and it doesn't change the comparison results you see. Affiliate revenue keeps NestPath free for first home buyers.

Compare The Market does not compare all plans in the market. See their website to view their range of brands.

Free to useNo obligationCompare the Market Australia

How to compare pet insurance like for like

To compare pet insurance like for like, line up policies for the same pet (species, breed and age) at the same cover level, then check the same points in each product disclosure statement (PDS): waiting periods, pre-existing conditions, the annual benefit limit and any sub-limits, the excess and benefit percentage, and the exclusions. Moneysmart says all policies are slightly different in what they do and don’t cover and what they cost.

  • Cover level. Moneysmart groups policies as accident only, accident and illness, and comprehensive. Some home and contents insurers also offer pet cover as an optional extra, which Moneysmart says may not be as comprehensive as a stand-alone policy.
  • Waiting periods. Most policies have a waiting period between signing up and claiming, and the length differs by type of treatment (see the waiting periods table below).
  • Pre-existing conditions. Moneysmart says most insurers won’t cover a condition your pet showed signs and symptoms of before being insured, and that it’s important to tell the insurer about any pre-existing conditions: if you don’t, you may not be covered.
  • Benefit limits. Check the annual limit the insurer will pay and any sub-limits for particular conditions or treatments.
  • Excess and benefit percentage. The excess is what you pay towards a claim, and the benefit percentage is the share of the eligible vet bill the policy pays. Some insurers apply the benefit percentage before deducting the excess, so check the order in the PDS.
  • Exclusions. Read the exclusions list in the PDS (see the exclusions section below).
  • Breed and age. Moneysmart says some breeds have health risks that make insurance either expensive or unavailable, and insurers may charge different premiums based on your pet’s age.
  • The target market determination. Insurance products have a target market determination (TMD) under ASIC’s design and distribution obligations, and ASIC has reviewed over 100 TMDs for general and life insurance products. Read the policy’s TMD alongside the PDS.
  • How claims are paid. Moneysmart says most insurers make you pay the vet fee in full and submit a claim after treatment, usually through a digital claims process where you upload receipts.

What an emergency vet bill actually costs in Australia

Many new pet owners budget for routine vet visits (typically a consultation plus an annual check-up and vaccinations). What can surprise people is the rare-but-real emergency, the kind that could break household budgets:

* After applicable excess. Many Australian comprehensive pet policies pay an 80% benefit percentage of eligible costs up to an annual benefit cap (commonly $15,000 to $25,000). Excess typically $100 to $250 per condition per year. Always check your specific PDS: caps and exclusions vary by insurer.
Emergency / surgeryMetro Australian specialist clinic cost (2024-25)% covered by typical comprehensive*
Cruciate ligament repair (dog)$5,000 to $7,000About 80%
Snake-bite emergency (anti-venom + ICU)$4,000 to $6,500About 80%
Hit-by-car trauma + surgery$6,000 to $12,000About 80%
Foreign-object ingestion surgery$3,500 to $6,000About 80%
Tick paralysis treatment$2,500 to $4,500About 80%
Cataract surgery (single eye)$3,000 to $4,500About 80%
Cancer treatment course (12 months)$8,000 to $15,000About 80% up to annual benefit cap
Annual preventive care (routine)Up to about $300Covered only if your policy includes it

The pattern: routine costs are predictable and budgetable. The $5,000 to $7,000 cruciate ligament or snake-bite emergency could land in a single month. Insurance is a budget defence to help with unexpected and large vet bills.

Is pet insurance worth it? The honest answer.

It depends on the pet, the policy, and your comfort with risk. The factors to weigh:

  • Breed and age: some breeds carry a higher risk of orthopaedic conditions (labradors, German shepherds, retrievers), and a younger pet has fewer conditions on record for pre-existing exclusions and waiting periods to affect.
  • Your savings: whether finding $5,000 to $7,000 for an emergency vet bill would be a struggle, or whether you have a $10,000+ savings buffer set aside for unexpected vet costs.
  • Older pets: for pets over 10 years old, premiums can climb sharply and pre-existing exclusions accumulate.
  • Cover level: Accident-only cover at around $20 to $30/month is a lower-cost option that covers emergencies such as snake bites and being hit by a car, without illness cover.

There are so many conflicting answers to “is pet insurance worth it?” because the question depends entirely on YOUR pet and YOUR risk tolerance. The financial test is simple: could you write a $7,000 cheque tomorrow without it disrupting your mortgage repayment, rent, or rates? If yes, you may not need to buy a policy. If no, buying a policy could be the better option.

The full breakdown, including what to weigh up for your pet, is in our guide Is pet insurance worth it in Australia?

Pet insurance for older dogs: what changes after age 8

Pet insurance gets trickier as your dog ages. Three things to know:

  • Premiums climb sharply. In the indicative cost table below, comprehensive cover for a mid-size dog is about $45 to $70/month at 1 to 3 years and $95 to $160/month at 8 to 10 years, on that table’s stated assumptions. Premiums typically rise with age.
  • Age-based exclusions kick in. Many insurers stop offering NEW policies once dogs are around 9 years old (caps vary by insurer), and quotes for cats are generally unavailable past 8 years through comparison services. If you don’t have a policy in place before your pet reaches those caps, options narrow.
  • Pre-existing conditions accumulate. Anything diagnosed before a policy is taken out (skin allergies, mild hip stiffness) is generally excluded from a new policy, and Moneysmart’s test is whether your pet showed signs and symptoms before being insured. Continuous cover from young age helps preserve the broadest cover.

If you already have an older dog with no current cover: a small number of insurers may still take new policies for older dogs, with premiums and cover terms that vary, so check availability with each insurer. Comparing shows which insurers will quote your specific dog’s age and breed combination.

Moneysmart says insurers may charge different premiums based on your pet’s age, and that insurance is most effective if you insure your pet while they’re young and keep the cover throughout the life of your pet. When you compare cover for an older dog, line up:

  • whether each insurer will take a new policy at your dog’s age (caps vary by insurer)
  • the benefit percentage and excess on offer
  • the annual limit and any sub-limits for the conditions you are most concerned about
  • how each policy treats anything your dog showed signs or symptoms of before cover, including bilateral conditions (see the exclusions section below)
  • whether accident only cover is offered alongside accident and illness cover

Excess + waiting periods explained

Two policy settings to understand before claim time:

  • Excess: typically $100 to $250 per condition per policy year. As an example, a $5,000 cruciate ligament surgery with an 80% benefit percentage and a $200 excess can pay out: ($5,000 minus $200) × 80% = $3,840 back. Some insurers apply the benefit percentage first and then deduct the excess, which produces a different outcome, so check your PDS for the order.
  • Waiting periods: the time between policy start and when cover for specific conditions activates. Common waiting periods (indicative; check the PDS) are: 2 to 14 days for accidents, 30 days for general illness, 6 months for cruciate ligament conditions, 12 months for some orthopaedic / chronic conditions. The cover you take out today only kicks in for those conditions after the waiting period passes. This is why timing matters: lock in cover when your pet is young and healthy, not when symptoms first appear.

Big mistake: assuming you can take out cover when you notice a problem. By the time symptoms are visible enough for you to act, the condition often pre-dates your policy, making it pre-existing and generally excluded. Cover only works as insurance against the UNKNOWN future bill.

Pet insurance waiting periods

A waiting period is the time between signing up and when you can claim for a type of treatment. Moneysmart says most pet insurance policies have one, and to check the PDS for the specific waiting periods for different types of treatment. Common waiting periods are short for accidents and longer for illness, cruciate ligament conditions and some orthopaedic conditions:

Indicative only: waiting periods vary by insurer and policy, so check the PDS for the exact lengths.
TreatmentCommon waiting period
Accidents2 to 14 days
General illness30 days
Cruciate ligament conditions6 months
Some orthopaedic and chronic conditions12 months

Accident cover often has no or a shorter waiting period than illness cover. Moneysmart lists treatment for illnesses that occur during the waiting period as a common exclusion.

Accident-only vs Illness vs Comprehensive

Moneysmart says policies can be broadly grouped into three cover levels, though every policy is slightly different:

Accident-only

Usually about $20 to $30 a month
  • Usually covers unexpected injury (hit-by-car, snake bite, ingestion, broken bones)
  • Often excludes illness (cancer, kidney disease, allergies)
  • Often no or shorter waiting periods than illness cover

Accident and illness

About $40 to $70 a month
  • Usually covers accidents and illness
  • Standard waiting periods apply
  • Annual benefit cap typically $10k to $20k

Comprehensive

About $55 to $95 a month
  • Usually covers accident and illness, and may include preventive care and some routine vet checks
  • Highest benefit caps ($15k to $25k+)

Note: indicative prices as at June 2026, drawn from insurers’ publicly available rate cards, for a 4-year-old desexed male labrador retriever (mid-size breed) living in New South Wales, on a $200 excess, an 80% benefit percentage and a $12,000 annual policy limit (benefit caps on comprehensive policies can be higher than this pricing example). Some breeds (French bulldogs, German shepherds) can carry premium loadings.

What each cover level usually includes

Cover descriptions from Moneysmart. Every policy is slightly different, so check the PDS.
Cover levelWhat Moneysmart says it coversWorth checking in the PDS
Accident onlyVet costs if your pet is in an accidentThat illness is not covered; the waiting period for accidents
Accident and illnessYour pet if it’s in an accident or if it gets sickWaiting periods for illness; pre-existing conditions; the annual limit and sub-limits
ComprehensiveAccidents, illness, preventative care and some routine vet checks such as vaccinations and wormingWhich routine care is included and how much it pays each year
Pet cover through home and contents insuranceOffered by some home and contents insurers as an optional extraMoneysmart says it may not be as comprehensive as a stand-alone policy

What’s typically covered (and what isn’t)

Standard Australian comprehensive pet insurance usually covers:

  • Surgery and hospitalisation
  • Diagnostic imaging (X-rays, ultrasound, MRI/CT)
  • Specialist consultations
  • Cancer treatment (within annual cap)
  • Tick paralysis treatment (some policies exclude tick bites, so check)
  • Snake-bite anti-venom + ICU
  • Cruciate ligament repair (after a 6-month waiting period)
  • Orthopaedic conditions (after a 12-month waiting period for some)

Usually EXCLUDED across pet insurance policies generally (check the PDS for your policy):

  • Pre-existing conditions diagnosed before policy start
  • Elective procedures such as desexing and microchipping
  • Routine and preventive care such as vaccinations and worming, unless your policy includes it. Moneysmart says comprehensive cover includes preventative care and some routine vet checks such as vaccinations and worming.
  • Dental cleaning, unless the policy includes it
  • Behavioural training
  • Breeding-related costs (whelping, c-sections for breeders)
  • Cosmetic procedures (tail docking, ear cropping)

Pet insurance exclusions, benefit limits and sub-limits

Every policy lists what it won’t pay for (the exclusions) and how much it will pay: an annual benefit limit across all claims, and on some policies smaller limits for particular conditions or treatments. Moneysmart says to read the PDS for the exclusions, and lists these as common exclusions:

  • Bilateral conditions: a pre-existing condition that affects a body part with a left and right version, such as eyes and ears.
  • Elective treatments, such as orthodontics or desexing.
  • Treatment for illnesses that occur during the waiting period.
  • Treatment for diseases where there is a known vaccine.

Moneysmart also says to check the policy for less common exclusions such as skin conditions and tick bites. An exclusion may be temporary or permanent: if your pet fully recovers from an acute issue, your insurer could agree to reinstate cover for it.

How the limits work

  • Annual benefit limit: the most the policy pays across all claims in one policy year.
  • Sub-limits: some policies set a lower limit for particular conditions or treatments inside the annual limit, so a large bill for that condition can reach the sub-limit first.
  • Benefit percentage: the share of each eligible vet bill the policy pays.
  • Excess: the amount you pay towards a claim. A higher excess usually means a lower premium; a lower excess means less to pay if you claim.

Moneysmart’s example of why limits matter: a procedure could cost $2,000 while the insurer only covers $500. Checking each limit in the PDS is part of comparing like for like.

How much does pet insurance cost in Australia

Indicative Australian premiums, compiled 2025 from insurers’ published rate cards, for a desexed pet on a $200 excess, an 80% benefit percentage, $15k to $25k annual benefit cap. Quotes for cats past 8 years are generally unavailable through comparison services. Premiums can vary significantly across insurers for similar cover, and comparing lets you review those differences.
Pet profileAccident-onlyComprehensive
Mid-size dog, 1 to 3 years$20 to $28/mo$45 to $70/mo
Mid-size dog, 4 to 7 years$24 to $32/mo$55 to $85/mo
Mid-size dog, 8 to 10 years$32 to $48/mo$95 to $160/mo
Cat, 1 to 7 years$15 to $22/mo$30 to $50/mo

For cats, see our cat insurance guide for what cover usually includes.

How to apply: 5-step process

  1. Apply while your pet is young and healthy. Pre-existing exclusions are the single biggest reason cover disappoints. Get cover BEFORE the first vet diagnosis you’d want to claim on.
  2. Compare via Compare the Market. Free to use, only takes a few minutes. Compare a range of Australian pet insurance brands side-by-side for your pet’s breed + age.
  3. Pick a cover level. Choose from Accident-only, Accident + Illness, or Comprehensive.
  4. Choose an excess. A higher excess usually means a lower premium; a lower excess means less to pay if you claim. Pick the balance that suits your budget.
  5. Mark the waiting-period dates. 30 days for illness, 6 months for cruciate ligament (indicative; check the PDS). Don’t assume cover is fully active on day one.

NestPath earns a commission if you take out a pet insurance policy through Compare the Market. No extra cost to you, and it doesn't change the comparison results you see. Affiliate revenue keeps NestPath free for first home buyers. *Compare The Market does not compare all plans in the market. See their website to view their range of brands.

Got a question we haven’t answered?

Drop the details and we’ll reply within 24 hours with a straight answer, not a sales pitch. If Compare the Market is the right next step, we’ll tell you. If it’s not, we’ll tell you that too.

Pet insurance for Australian homeowners: common questions

How do I compare pet insurance policies like for like?

Compare policies for the same pet (species, breed and age) at the same cover level, then check the same points in each product disclosure statement (PDS): waiting periods, pre-existing conditions, the annual benefit limit and any sub-limits, the excess and benefit percentage, and the exclusions. Moneysmart says all policies are slightly different in what they do and don’t cover and what they cost.

What does pet insurance not cover?

It depends on the policy, so read the exclusions in the PDS. Moneysmart lists these common exclusions: bilateral conditions, elective treatments such as orthodontics or desexing, treatment for illnesses that occur during the waiting period, and treatment for diseases where there is a known vaccine. It also says to check for less common exclusions such as skin conditions and tick bites. Pre-existing conditions are generally excluded.

What is a bilateral condition in pet insurance?

Moneysmart describes a bilateral condition as a pre-existing condition that affects a body part that has a left and right version, such as eyes and ears. It lists bilateral conditions as a common exclusion, so a condition in one eye or ear before cover starts can affect cover for the other side too. Check how the PDS treats them.

Can I get pet insurance with no waiting period?

Accident cover often has no or a shorter waiting period than illness cover, while illness, cruciate ligament and some orthopaedic conditions usually have longer waiting periods. Moneysmart says most pet insurance policies have a waiting period and to check the PDS for the specific waiting periods for different types of treatment.

How do I complain about a pet insurance claim?

Moneysmart says to contact your insurer’s internal dispute resolution department first, for example if your insurer rejects your claim. If you can’t reach an agreement, you can contact the Australian Financial Complaints Authority (AFCA) for free, independent dispute resolution.

Is pet insurance worth it in Australia?

Depends on your pet and your savings. The honest financial test: could you write a $7,000 cheque tomorrow for an emergency vet bill without disrupting your mortgage, rent or rates? If yes, you may not need to buy a policy. If no, buying a policy could be the better option. Factors that make cover more relevant include a pet under 8 in a higher-risk breed (labradors, retrievers, German shepherds, French bulldogs) where orthopaedic + chronic conditions are common, and difficulty finding $5,000 to $7,000 for an emergency vet bill.

What does an emergency vet bill cost in Australia?

The bills that could break a new owner’s budget: cruciate ligament repair $5,000 to $7,000, snake-bite emergency $4,000 to $6,500, hit-by-car trauma $6,000 to $12,000, tick paralysis treatment $2,500 to $4,500, foreign-object ingestion surgery $3,500 to $6,000, cancer treatment $8,000 to $15,000 across a year. Routine preventive care could be about $300 a year or less, and is covered only if your policy includes it (Moneysmart says comprehensive cover includes preventative care and some routine vet checks such as vaccinations and worming). The gap between the routine number and the emergency number is what insurance helps with.

How much does pet insurance cost per month in Australia?

Indicative Australian premiums, compiled 2025 from insurers’ published rate cards, on a $200 excess, an 80% benefit percentage and a $15,000 to $25,000 annual cap: mid-size dog 1 to 3 years comprehensive $45 to $70/month, 4 to 7 years $55 to $85/month, 8 to 10 years $95 to $160/month. Cats 1 to 7 years $30 to $50/month; quotes for cats past 8 years are generally unavailable through comparison services. Accident-only cover is generally cheaper: around $20 to $48/month for a mid-size dog depending on age, and $15 to $22/month for a cat aged 1 to 7. Premiums can vary significantly across insurers for similar cover.

What is a pet insurance waiting period?

The time between when your policy starts and when cover for specific conditions activates. Common waiting periods (they vary by insurer, so check the PDS): 2 to 14 days for accidents, 30 days for general illness, 6 months for cruciate ligament conditions, 12 months for some orthopaedic and chronic conditions. The cover you take out today only kicks in for those conditions after the waiting period passes, which is why pet insurance is something to take out BEFORE you see symptoms, not after.

What is pet insurance excess and how does it work?

Excess is the amount you contribute towards an eligible claim; what the insurer then pays depends on the benefit percentage, the limits and the order the PDS applies them. Typically $100 to $250 per condition per policy year in Australia. As an example, on a $5,000 cruciate ligament surgery with an 80% benefit percentage and a $200 excess: ($5,000 minus $200) × 80% = $3,840 paid to you. Some insurers apply the benefit percentage first and then deduct the excess, which produces a different outcome, so check your PDS for the order. A higher excess usually means a lower premium but more to pay on every claim.

Does pet insurance cover pre-existing conditions?

Generally not. Moneysmart says most insurers won’t cover pre-existing medical conditions, meaning a condition your pet showed signs and symptoms of before being insured, and definitions vary between insurers, so check the PDS. Moneysmart also says an exclusion may be temporary or permanent: if your pet fully recovers from an acute issue, your insurer could agree to reinstate cover for it. This is a big disappointment for owners who take out cover after their pet starts showing symptoms. Cover taken out while a pet is young and healthy has fewer conditions on record to exclude.

Is pet insurance worth it for an older dog?

Trickier. Premiums typically climb after age 8. Many insurers stop offering NEW comprehensive policies as dogs age, caps vary by insurer, and some specialised insurers still accept older dogs with reduced cover. If your older dog already has a long vet history, the pre-existing exclusions can leave the policy meaningfully thinner than the price suggests. Compare to see which insurers will quote your specific age and breed. Accident-only cover can be a lower-cost option for older pets.

Is pet insurance worth it for a puppy or kitten?

A young pet is when cover is often cheapest, waiting periods are easiest to clear without symptoms appearing, and pre-existing exclusions are generally non-existent. Moneysmart says insurance is most effective if you insure your pet while they’re young and keep the cover throughout the life of your pet; what stays claimable still depends on the policy terms. The bills puppies generate (eating things they shouldn't, accidents during exploration, congenital condition discovery) can arrive early. If the person you bought your pet from also sells pet insurance, Moneysmart says you can complain if they did not wait four days after your pet purchase before selling you the insurance.

What is the difference between accident-only and comprehensive pet insurance?

Accident-only covers unexpected injury (hit-by-car, snake bite, foreign object ingestion, broken bones) and excludes illness (cancer, kidney disease, allergies, chronic conditions). It is cheaper (about $20 to $30/month for a 4-year-old labrador in our pricing example) and often has shorter waiting periods. Comprehensive covers both accident AND illness, and Moneysmart says it covers preventative care and some routine vet checks such as vaccinations and worming. Comprehensive could be $55 to $95/month for the same example dog. Accident-only can be a lower-cost option.

Can I claim multiple conditions on pet insurance in the same year?

Yes, up to the annual benefit cap. On policies where the excess applies per condition, two unrelated conditions can mean two excesses to pay. The annual benefit cap is the total amount the insurer will pay across all claims in one policy year, typically $15,000 to $25,000 on comprehensive. Sub-limits sometimes apply to specific categories (cancer treatment may cap at $10,000 within the broader $20,000 annual cap). Always check the PDS for the specific caps and sub-limits.

Does pet insurance cover dental cleaning?

Moneysmart says comprehensive cover includes preventative care and some routine vet checks such as vaccinations and worming. It does not mention dental cleaning, so check the PDS for whether dental cleaning is covered and any yearly limit.

Can I switch pet insurance providers?

Yes, but with caution. Moneysmart says anything previously claimed for would be considered a pre-existing condition by the new insurer, so it is generally excluded. Switching carries less risk of new exclusions when a pet has no claims history, while switching after years of claims often creates large gaps in coverage. The new policy’s waiting periods apply from its start date, so compare start dates and waiting periods before cancelling the old policy.

What is the maximum age I can take out pet insurance in Australia?

Many insurers stop offering NEW comprehensive policies as pets age, commonly around 9 for dogs, with caps varying by insurer, and quotes for cats are generally unavailable past 8 years through comparison services. New applications past an insurer’s age cap are usually not accepted. Moneysmart says insurance is most effective if you insure your pet while they’re young and keep the cover throughout the life of your pet.

How quickly does pet insurance pay out a claim?

Moneysmart says most insurers make you pay the vet fee in full and submit a claim after treatment, usually through a digital claims process where you upload receipts. For insurers that subscribe to the General Insurance Code of Practice, and for products it covers, the Code says that once the insurer has all relevant information and has completed its enquiries, it decides whether to accept or deny the claim within 10 business days, and makes the decision within 4 months of receiving the claim unless an exception applies, with written reasons if it denies the claim. That is a decision timeframe, not a payment timeframe, so ask your insurer whether it subscribes to the Code and how long payment takes.

Can I cancel my pet insurance and get a refund?

Check the PDS for the cooling-off period and how refunds work if you cancel after it. If a policy renews automatically, insurers that subscribe to the General Insurance Code of Practice say, for products the Code covers, that they will remind you about the automatic renewal process at the time of purchase and at each renewal, and that you can opt out of it.
Also worth a look: many homeowners pair pet cover with health insurance (private hospital and extras cover, which can also help with possible MLS and LHC charges), income protection (income replacement if illness keeps them off work), and life insurance (support for the family in the event you pass away).